

 Back to Blogs
How Can You Finance Home Improvement Projects?
Your home should be a place of comfort, style, and lasting value. But when windows start drafting, doors won't seal properly, or your siding is showing its age, the cost of repairing everything can feel overwhelming.
There’s some good news, though: You don't have to drain your savings or put off essential upgrades just because the upfront cost feels too high. That’s because home improvement financing gives you the flexibility to invest in your home now and pay over time, so you can start enjoying a more comfortable, energy-efficient space without the wait.
If you’re a Knoxville-area homeowner planning to replace every window, install energy-efficient doors, or refresh your exterior with new siding, understanding your financing options will help you tackle your renovations without breaking the bank. Let's break down how home improvement financing works, what affects your terms, and how to choose the best option for your project.
Why financing makes sense for home improvements
Most homeowners don't have thousands of dollars sitting around waiting to be spent on renovation projects. And even if you do have savings set aside, using all of it on one remodeling project can leave you without a safety net for unexpected expenses.
That's where financing comes in. It allows you to:
- Spread the cost of your home improvement project across manageable monthly payments
- Preserve your cash flow
- Keep your emergency fund intact
But there's another benefit, too: timing. Energy-efficient windows and doors can start lowering your utility bills immediately, which means the money you save each month can help offset your loan payment. In other words, your home improvement can actually pay for itself over time.
Plus, financing gives you the freedom to tackle bigger projects all at once instead of piecemealing them over several years. You can upgrade your whole home's exterior in one coordinated effort, enjoying the full benefits of improved comfort, curb appeal, and energy efficiency right away.
Understanding your home improvement financing options
When it comes to paying for home renovations, there are several paths to choose from. Each option comes with its own set of pros and cons, and the right choice depends on your financial situation, credit history, and the scope of your project.
Let's take a closer look at the most common ways to finance home improvements.
Personal loans for home renovations
A personal loan is an unsecured loan, which means you don't have to put up your home as collateral. You borrow a lump sum and repay it in fixed monthly payments over a set loan term, typically ranging from 12 to 84 months (though 36 months is a popular choice for mid-sized projects).
Because these loans aren't secured by your property, approval is based largely on your credit score and income. If you have a solid credit history, you may qualify for competitive interest rates. However, borrowers with lower credit scores might face higher rates or stricter repayment terms.
Personal loans work well for homeowners who want quick access to funds without tapping into their home's equity. They're also a smart option if you're planning a straightforward exterior remodeling project with a clear budget, like installing new windows or doors.
Home equity loans and HELOCs
If you've built up equity in your home, a home equity loan or home equity line of credit (HELOC) can be a powerful financing tool. Both options let you borrow against the value of your property, often at lower interest rates than personal loans or credit cards.
A home equity loan gives you a lump sum upfront with a fixed interest rate and predictable monthly payments. It's ideal if you know exactly how much your project will cost and want the stability of consistent payments over the life of the loan.
A HELOC, on the other hand, works more like a credit card. You're approved for a credit line that you can draw from as needed, and you only pay interest on what you actually use. HELOCs typically come with variable interest rates, which means your monthly payment can fluctuate.
While these options can offer lower rates, they do come with a tradeoff: your home serves as collateral. That means if you can't make your payments, you risk foreclosure. For that reason, home equity financing is best suited for homeowners with stable income and a clear plan for repayment.
Credit cards and their role in smaller projects
For smaller home improvement projects or quick fixes, a credit card might seem like the easiest solution. In some cases, it can be, especially if you have access to a card with a promotional 0% APR period.
If you can pay off the balance before the promotional period ends, you'll avoid interest charges altogether. That makes credit cards a practical choice for:
- Minor upgrades
- Repairs
- Smaller projects with a clear, limited scope
However, once that introductory period expires, interest rates can jump significantly – often into the high teens or even twenties. For larger projects that take months to pay off, those high rates can add hundreds or thousands of dollars to the total cost. That's why credit cards are generally best for homeowners who can pay quickly or who are working on smaller-scale renovations.
What affects your financing terms?
Not all financing offers are created equal. The terms you're offered – your interest rate, monthly payment, and overall loan cost – depend on several factors, most of which are within your control or at least worth understanding before you apply.
Credit score and credit history
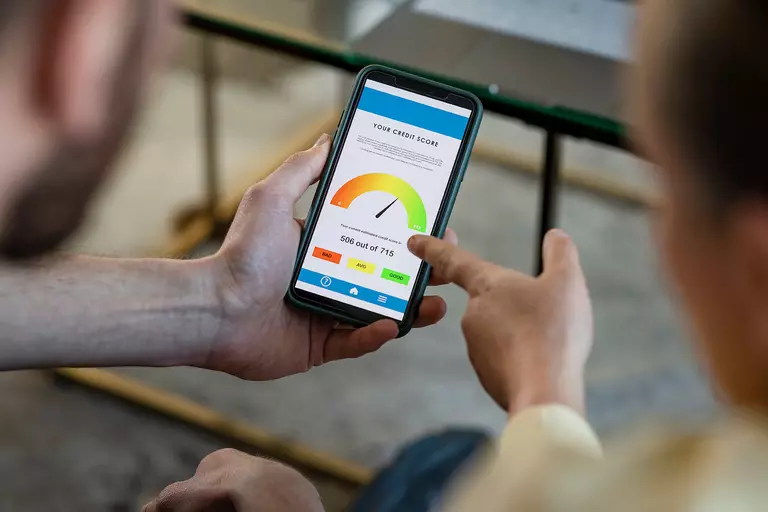
Your credit score is one of the most important factors lenders consider when determining your interest rate. Simply put, a higher score signals to lenders that you're a lower risk, which typically translates to better rates and more favorable terms.
If your credit score is in the mid-600s or higher, you'll likely qualify for competitive rates on most types of home improvement loans. Scores above 700 often unlock the lowest rates available. On the flip side, if your credit history shows missed payments or high debt levels, you may face higher interest rates or need to provide additional documentation.
Loan term length and monthly payments
The length of your loan term directly affects both your monthly payment and the total amount you'll pay over time. Shorter terms – like 24 or 36 months – mean higher monthly payments, but you'll pay less in interest overall. Longer terms, such as 60 or 84 months, lower your monthly payment but increase the total cost of the loan.
Choosing the right loan term is all about balance. If you can comfortably afford higher monthly payments, a shorter term will save you money in the long run. But if your budget is tight or you're managing multiple financial priorities, a longer term can keep your payments manageable without stretching your finances too thin.
Interest rates: fixed vs. variable
When comparing financing options, you'll come across two main types of interest rates: fixed and variable.
A fixed interest rate stays the same for the entire life of the loan, which means your monthly payment won't change. This predictability makes budgeting easier and protects you from rising rates if the market shifts. Fixed rates are a smart choice if you value stability and want to know exactly what you'll owe each month.
A variable interest rate, on the other hand, can fluctuate based on market conditions. While variable rates often start lower than fixed rates, they can increase over time, potentially raising your monthly payment. This option works best for borrowers who plan to pay off their loan quickly or who are comfortable with some uncertainty in their payment amounts.
How do you choose the best financing option for your home improvement project?
With so many financing options available, how do you decide which one is right for you? Start by asking yourself a few key questions:
- First, what's the scope of your project? If you're replacing a few windows or installing a single door, a smaller personal loan or even a credit card with a promotional rate might be all you need. But if you're planning a full exterior renovation – new windows, doors, and siding – you'll likely need a larger loan with a longer repayment term.
- Next, consider your financial situation. Do you have equity in your home? Are you comfortable using your property as collateral? If so, a home equity loan or HELOC could offer the lowest rate. If not, or if you'd rather keep your home out of the equation, a personal loan provides a safer, more straightforward option.
- Your credit score matters, too. If you have excellent credit, you'll have access to the best rates across the board. If your credit is less than perfect, you might need to focus on lenders who specialize in working with borrowers in your situation – or consider improving your score before applying.
- Finally, think about timing. Do you need funds quickly, or can you afford to wait through a longer approval process? Personal loans and retailer financing programs (like the kind we offer at Window World of Knoxville) tend to move faster than government-backed loans or traditional home equity products.
The benefits of financing your renovation through Window World of Knoxville
While banks and credit unions offer plenty of home improvement financing options, there's something to be said for working directly with the company handling your renovation. At Window World of Knoxville, we've partnered with trusted lenders to offer financing solutions designed specifically for homeowners investing in windows, doors, and siding.
Simplified approval process
One of the biggest advantages of financing through Window World is simplicity. Instead of filling out applications at multiple banks or navigating complicated online portals, you can explore your financing options during your free consultation or when you're ready to move forward with your project.
Our team works with you to find a financing plan that fits your budget and timeline. The approval process is straightforward, with quick decisions and minimal paperwork.
Competitive rates and flexible terms
Just because you're financing through a home improvement company doesn't mean you're stuck with subpar terms. Window World of Knoxville's financing options are designed to be competitive with what you'd find at traditional lenders, with flexible repayment terms that can be tailored to your financial situation.
No need to negotiate with multiple lenders
When you finance through Window World of Knoxville, you're working with a single point of contact for both your renovation and your financing. That means no juggling phone calls with different banks, no comparing confusing loan offers, and no wondering if you're getting the best deal.
Plus, financing through us means your loan is built around the actual cost of your remodeling project. There's no guessing about how much to borrow or worrying that you've overestimated (or underestimated) your needs. We'll provide a clear quote, and your financing will match it.
Start your home improvement project today with flexible financing
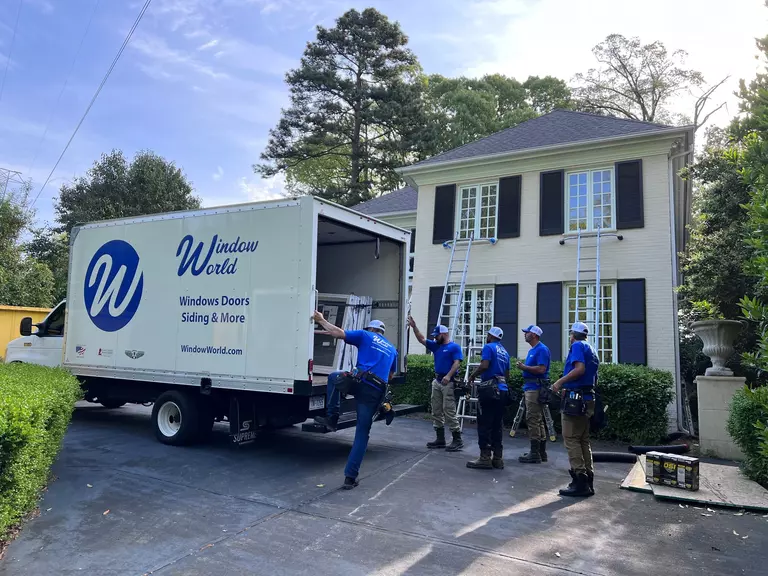
You don't have to wait years to upgrade your home or sacrifice your financial security to make it happen. With the right financing option, you can invest in energy-efficient windows, beautiful replacement doors, and durable siding that will improve your comfort, lower your utility bills, and boost your home's curb appeal – all while keeping your monthly budget intact.
At Window World of Knoxville, we're here to help you every step of the way, from choosing the perfect products to finding a financing plan that fits your needs. Whether you're replacing a few windows or transforming your entire exterior, we'll make the process simple, stress-free, and affordable.
Ready to get started? Contact Window World of Knoxville today to schedule your free consultation and explore flexible financing options that make your dream home makeover possible.